
Rising Interest Rates Are Dividing the Market
September 25, 2026
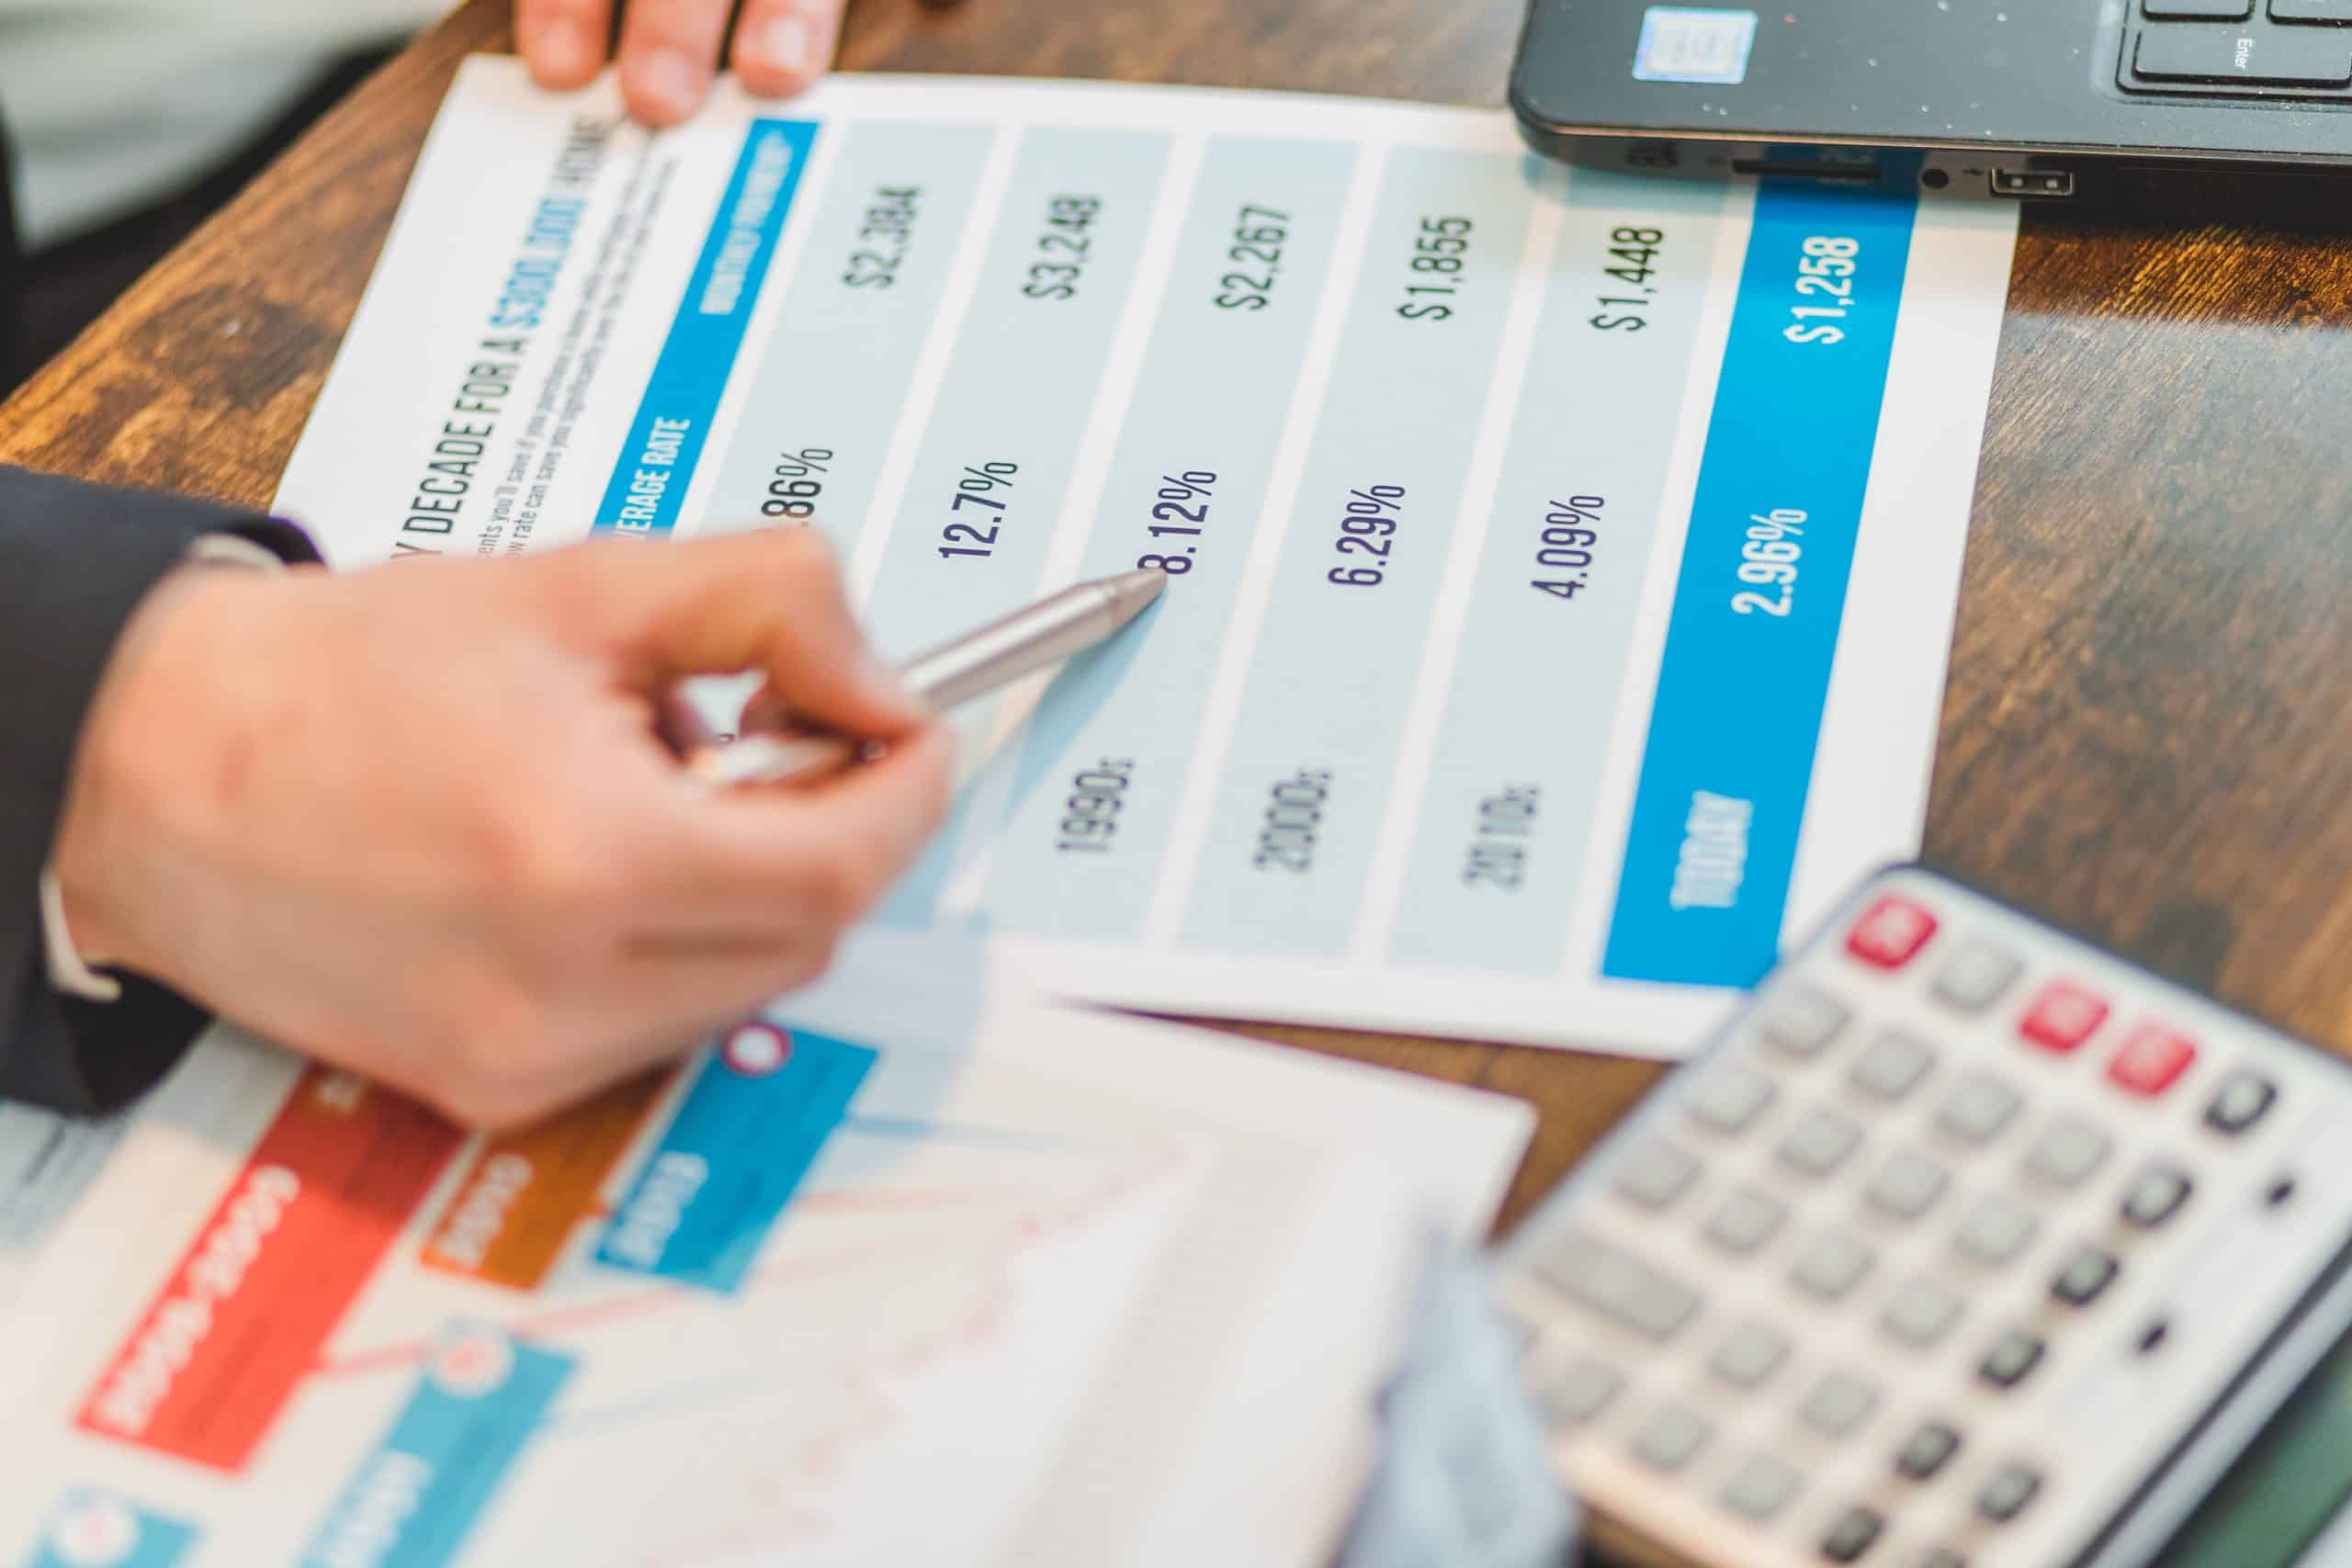
Inflation is raising its ugly head….again.
It was only four years ago that we were sitting contentedly in a 3% rate, post-pandemic world, when our administration suddenly woke up and realized that inflation was running rampant in just about every sector of the economy, especially housing. Their response was belated but brutal: 11 different rate hikes by the Federal Reserve over a period of just 16 months.
Even though home mortgage interest rates are not tied to the prime rate, but rather tend to follow the 10-year Treasury yield, it didn't matter. Home interest rates rocketed to 7% over that period and ultimately settled into the 6% range, still double what the same loan would have cost just 2 years earlier.
That rapid ascent in interest rates essentially ripped the bottom out of the local real estate market, as sales volume and prices plummeted from the highs of the first half of 2022 and have remained on a slow climb back ever since, as home buyers begrudgingly accepted 6% as the new norm.
Well, guess what? It's happening again. Only this time, it's in slow motion.
With gas pushing $7 per gallon and grocery costs skyrocketing, the Federal Reserve did something it hasn't done in three years – it voted to raise the prime rate, with the specter of a second rate hike in December being very likely.
The bond market, and consequently the home mortgage industry, tends to predict these moves in advance and react accordingly. If you're currently in the market to purchase a home, you've undoubtedly noticed that rates have been steadily creeping upward over the past month, well in advance of the Fed's announcement.
As of this morning, the average 30-year fixed-rate mortgage is now once again over 7% — the highest level in two years — and there are even whispers about it hitting as high as 8% before the end of the year.
It would be very logical to conclude that this would once again kneecap the housing market. But interestingly, it all depends on which housing market you're referring to.
A Tale of Two Markets
This month, I had two listings on the market at the same time while these rates were rising. One was a 4BR home in San Carlos that was listed at around $2.4M, and the other was a 5BR home in Atherton listed for nearly $5.9M. Which home do you think got more viewings, showings, and offers?
The most logical answer would be the San Carlos home, since it's in the entry-level price range where there are more buyers (I know, it's laughable that $2.4M is considered “entry-level,” but just roll with me on this).
But it was the Atherton house — by a mile.
There are a few reasons for this apparent paradox. First, entry-level buyers tend to borrow more money and put less down, so even a small increase in their loan rate greatly impacts their monthly payment. As rates were rising, the buyers were dropping like flies on the San Carlos home.
Conversely, the Atherton home received 6 offers in one week and sold well over the list price. You might immediately assume that this happened because all of the offers were cash, and they were immune to interest rate variations. But half of the offers actually had substantial loans, which I found surprising (more on that in a second).
This isn't an isolated incident. There are countless stories about massive overbidding that are taking place right now in luxury markets like San Francisco and Atherton. It's almost routine to hear about a home in these markets that fetched a 7-figure premium over its list price.
So on one end of the spectrum, buyers are being punished, and at the wealthier end, the market is on fire. It's essentially the definition of a K-shaped economy.
But back to the luxury buyers and loans. How is it possible, or even feasible, for someone to absorb a 7% loan in the luxury price range? The answer is that they are not. What is usually happening in that situation is that the borrower can qualify for a “relationship discount” by moving a significant chunk of assets over to that particular lending institution. So instead of paying 7%, they're probably in the low 5% range.
The question then becomes, “If they have so many assets, then why not just pay cash for the house?” It has to do with the equity markets, and how these buyers hold their fortunes. If a buyer has much of their assets tied up in stocks, liquidating them to purchase the home usually triggers a massive taxable event. It's just cleaner to borrow the money at a reasonably favorable rate.
But there are many buyers who have the liquid cash to purchase a home, but they still opt for an attractively reduced loan because they believe they can make a greater return on their money in the market, so borrowing at 5% still pencils out better for them.
Key Takeaways:
So what am I trying to prove in this rambling post? When interest rates rise, it impacts different segments of the market differently. Here are the key points:
- Entry-level and first-time home buyers are usually impacted more severely when interest rates rise.
- All-cash buyers are immune from home mortgage interest rate increases, and they benefit when the buying power of their competition is reduced.
- Wealthy buyers can qualify for “relationship rates,” which are substantially lower than what's available on the open market.
- Buyers with substantial cash reserves still opt to borrow at favorable rates because they can invest those same funds and get a better return on their investment.
In other words, you gotta have money to make money.
If home mortgage interest rates do indeed get near 8%, I don't see how it's not going to negatively impact the San Carlos market. If you recall from this post, about 85% of the homes purchased in San Carlos over the past 5 years were financed with a bank loan.
And not all rate increases are created equal. When the first digit clicks up, it's a huge emotional (and financial) hurdle for buyers. Seeing rates go from a 6 to a 7 is traumatic enough.
Just wait until it turns into an 8.
Posted in: